Annual Expense Sinking Fund Planning for Predictable Irregular Bills
Unexpected annual bills can strain even a careful budget; annual expense sinking fund planning spreads those costs across the year. This guide shows how to map a planned expense calendar, organize savings buckets, and track sinking funds so irregular expenses feel routine instead of disruptive.
This story is part of Esgamesol's practical reading library across everyday topics.
Why Annual Expense Sinking Funds Matter
Annual Expense Sinking Fund Planning breaks large, occasional bills into manageable monthly amounts so they do not disrupt your cash flow later in the year. Instead of treating car insurance, property taxes, membership dues, or annual subscriptions as emergencies, you plan for them and save gradually. This improves your yearly budget categories because it forces you to look beyond routine monthly costs like rent, groceries, and utilities. By listing expenses that appear once or twice a year and giving each a savings target, you spread their impact across the full year instead of letting it hit a single paycheck.
This forward-looking approach is the core of irregular expense planning and annual bill preparation. A sinking fund can be a labeled savings bucket, a separate account, or a digital category you contribute to on a schedule. Each small contribution helps cover planned bills that might otherwise lead to overdrafts, late fees, or extra debt. When these funds sit inside your overall budget, they reveal what you truly spend in a year and show which commitments you can realistically afford. Over time, this structure makes money management more predictable and less stressful, because large bills move from surprise events to known, scheduled obligations.
Mapping Out Your Planned Expense Calendar
A planned expense calendar helps turn irregular costs into predictable items in your yearly budget categories. List every non‑monthly bill and seasonal cost, including annual insurance premiums, car registration, property taxes, subscriptions, school fees, holiday gifts, and routine medical or dental visits. Note the month and approximate due date for each expense so you can see how they are spread across the year. This overview supports accurate annual bill preparation because you are working from a clear schedule instead of guessing when costs will appear.
After you see the full year, link the calendar to your irregular expense planning and monthly cash flow. Group similar costs into categories that reflect how you manage money, such as transportation, housing and utilities, healthcare, kids and school, and celebrations or travel. For each group, decide how much to save each month so your sinking fund has enough when the bill arrives. Many households use separate savings buckets or a digital sinking fund tracker to monitor progress. Reviewing and updating your planned expense calendar at least once a year keeps your annual expense sinking fund planning aligned with real bills rather than outdated estimates.
| Expense Type | Typical Month | Suggested Category | Calendar Checkpoint |
|---|---|---|---|
| Insurance premium | Policy renewal month | Housing or Transportation | Verify renewal date and coverage |
| Car registration | License renewal month | Transportation | Confirm due window with local agency |
| Property tax | Tax billing period | Housing and utilities | Align with mortgage or escrow timing |
| Subscriptions and memberships | Sign-up anniversary month | Personal or Entertainment | Review need and possible cancellations |
| School and activity fees | Start of term or season | Kids and school | Coordinate with academic calendar |
| Holiday gifts and travel | Planned holiday season | Celebrations or travel | Set earlier savings start month |
Common Categories of Irregular and Annual Expenses
When you map out irregular expense planning as part of overall annual expense sinking fund planning, start by listing yearly budget categories that seldom appear in a monthly budget. These often include property taxes, vehicle registration, professional license renewals, annual subscriptions, and insurance premiums billed semiannually or annually. Many households also budget for predictable but non‑monthly costs such as routine car maintenance, expected home repairs, seasonal yard work, and periodic technology replacements like phones or laptops.
Annual bill preparation should also include events that follow the calendar rather than a monthly cycle. Holiday gifts and travel, back‑to‑school shopping, sports and activity fees, and major celebrations such as weddings, graduations, or milestone birthdays are common examples. People often add medical and dental costs not covered by insurance, pet care, and occasional wardrobe or furniture updates. Grouping these items into clear yearly budget categories turns them into planned expenses instead of surprises, so they can be scheduled on a planned expense calendar and funded in advance through sinking funds.
Setting Up Household Savings Buckets
Once you have listed your annual and irregular costs, the next step in annual expense sinking fund planning is to group them into clear household savings buckets. Instead of treating every single bill as a surprise, you can organize them into broad yearly budget categories such as housing, transportation, insurance, health, kids or pets, and seasonal spending. For each category, total the expected yearly amount and divide by twelve to arrive at a monthly savings target. This approach turns large, occasional bills into smaller, predictable transfers that are easier to fit into a regular budget, while still reflecting how your household actually spends throughout the year.
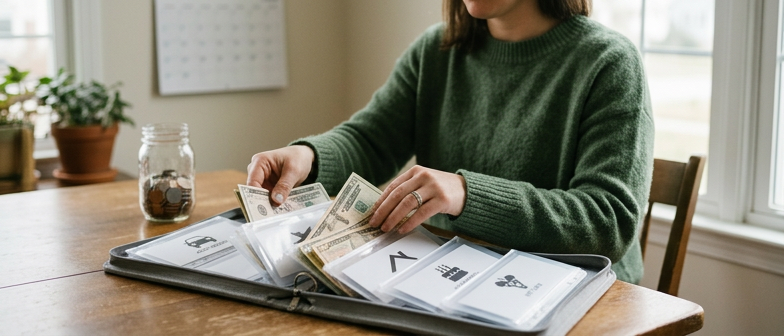
To keep these buckets practical, decide how you will track them and move money consistently. Some people open separate savings subaccounts and label each one, while others use a simple sinking fund tracker in a spreadsheet or budgeting app to monitor balances within a single account. The method matters less than making sure the categories match your real obligations and that transfers happen on a regular schedule. Over time, this structure helps your annual expense sinking fund planning become a routine part of money management, supporting a more stable cash flow and reducing the stress of once-a-year bills arriving without a plan.
Choosing Where and How to Hold Each Bucket
When you set up household savings buckets for annual and irregular expenses, decide whether to keep each one in a separate account or combine them. Separate accounts for big categories like insurance or property tax make it easy to see if each annual expense sinking fund is on track. A single high‑yield savings account can also work if you use a clear sinking fund tracker to show how much of the total balance belongs to each planned expense.
How you track these buckets matters as much as where the money sits. A spreadsheet, budget app, or notebook can serve as your sinking fund tracker if you update deposits and withdrawals and tie them to the bank balance. Some households use named sub‑accounts so the setup mirrors their planned expense calendar, while others keep one account and rely on simple, consistent record‑keeping.
Using a Sinking Fund Tracker All Year Long
A simple sinking fund tracker is the backbone of annual expense sinking fund planning because it shows, in one place, what you have set aside for upcoming costs and how those balances are changing. Whether you use a spreadsheet, a budgeting app, or a paper log, the tracker should list each savings bucket, its goal amount, the monthly or paycheck contribution, and the current balance. As you follow your planned expense calendar for insurance premiums, car registration, or holiday travel, record every deposit and withdrawal so the numbers stay accurate. Consistent tracking turns irregular expense planning from guesswork into a routine and helps you see early if a category is building too slowly or if you are drawing from it more often than expected.
Over the year, the tracker becomes a tool for adjusting your yearly budget categories as your household needs change. When an annual bill increases, update the goal amount and spread the higher cost across the remaining months instead of scrambling at the due date. If one savings bucket is rarely used while another is always short, reassign part of your regular contributions so they match real spending. Reviewing balances at least monthly and comparing them to your calendar of planned expenses keeps each sinking fund aligned with current priorities. Treating the tracker as a living document lets you make gradual adjustments that keep annual bill preparation and other non-monthly costs on track.
Q&A
-
What is annual expense sinking fund planning?
It means turning large, irregular bills into small monthly savings. You set aside money all year for costs like insurance or property taxes so they don’t blow up your budget when they come due. -
How do I create a planned expense calendar for irregular bills?
List every non‑monthly bill and seasonal cost, note approximate due months, and total each one. This calendar shows when big expenses hit so you can spread savings across the year. -
Which yearly budget categories are often missed?
People skip car registration, professional dues, annual subscriptions, routine car work, and occasional home or yard projects that still repeat each year. -
How can I set up household savings buckets for these costs?
Group expenses into buckets like housing, transportation, insurance, health, and seasonal spending. Estimate each bucket’s yearly total and divide by twelve to get a monthly sinking fund amount. -
What is a sinking fund tracker and how do I use it?
It’s a log or app showing each bucket, goal, deposits, and balance. Update it whenever you add or withdraw so you know if each planned expense is on target.